
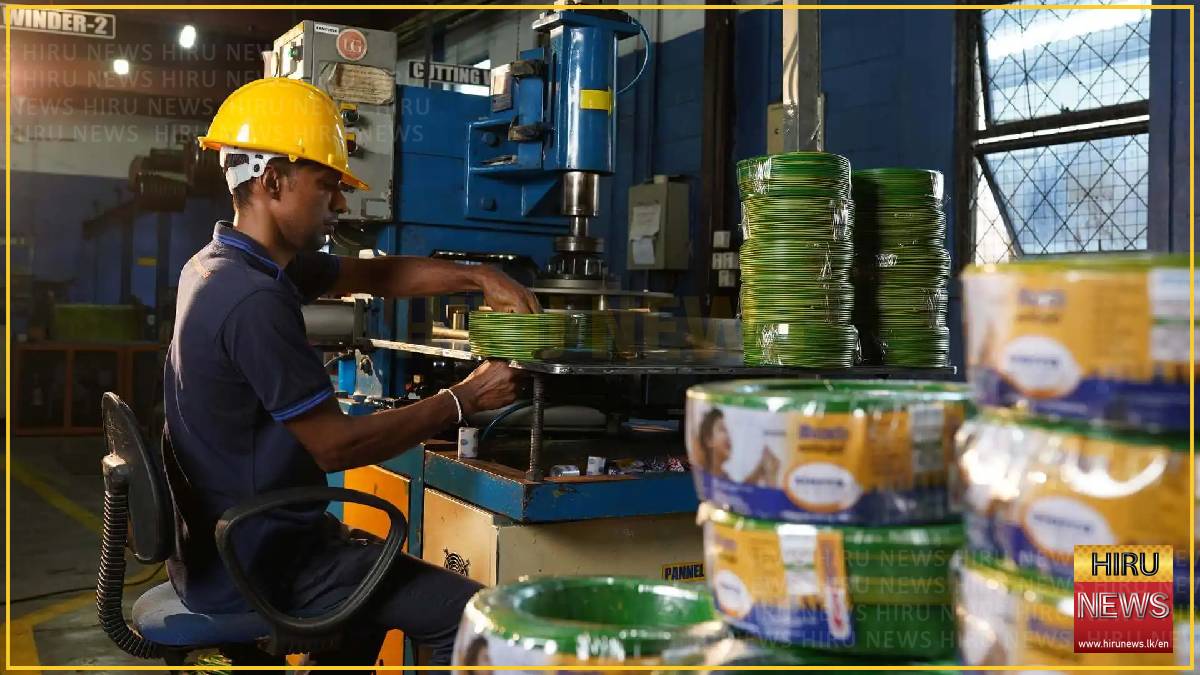
Fitch Ratings has affirmed Sierra Cables PLC’s National Long-Term Rating at ‘A+(lka)’ with a Stable Outlook, citing the company’s earnings growth prospects, leading position in the domestic market and expanding export business, while highlighting concerns over narrowing margins, rising debt and working-capital requirements.
The rating reflects Fitch’s assessment of Sierra’s Standalone Credit Profile (SCP) at ‘a+(lka)’, which it considers comparable to that of its parent, LOLC Holdings PLC. The agency expects earnings to grow but anticipates pressure from declining margins and higher leverage. Sierra’s relatively small operating scale, exposure to cyclical markets and vulnerability to commodity price movements also weigh on its credit profile.
Its established domestic market position and growing export volumes provide support. However, limited liquidity headroom means the company remains dependent on lenders renewing its working-capital facilities. Fitch also identified an increase in related-party transactions as a factor that has weakened the credit profile.
Domestic and export sales drive revenue growth
Fitch expects Sierra’s strong position in the project segment and its cost advantage over competitors to help secure orders and sustain revenue growth.
The company’s revenue increased by 73% to Rs. 16.0 billion in the financial year ended March 31, 2026 (FY26), supported by higher domestic and export sales.
Domestic growth has been supported by efforts to expand the dealer network, increase promotional activity and strengthen the sales force. However, revenue from tenders, Sierra’s highest-margin sales channel, declined in the fourth quarter of FY26 and first quarter of FY27 following the restructuring of the Ceylon Electricity Board. Management expects tender activity to recover and says the company has regained momentum in recent bids.
Export growth puts pressure on margins
Although exports contributed approximately Rs. 5.0 billion to revenue in FY26, Fitch expects margins from overseas sales to remain thin as Sierra prioritises sales volumes over pricing amid higher costs and competition. Most of the company’s exports during the period were shipped to the United States.
Sierra plans to invest around Rs. 2.0 billion in additional capacity dedicated to exports. However, higher copper and aluminium prices are adding to production costs, while competition from local manufacturers and imported cables limits the company’s ability to pass on these increases to customers.
Fitch therefore expects margin recovery to remain constrained.
Working-capital requirements remain high
The agency expects Sierra’s working-capital cycle to improve slightly but remain extended at around 240 days over the next 12 months, compared with 250 days in FY26.
The shift from cash sales to credit transactions has increased the company’s working-capital requirements, with more than 95% of sales now made on credit. Receivable days increased to 112 in FY26 from 64 in FY25, and Fitch expects the figure to rise to around 130–140 days during FY27–FY28.
Inventory days have also exceeded 150 following recent sales growth, although Fitch expects them to decline to approximately 130 days. Payable days are expected to remain stable.
Debt-funded expansion keeps leverage elevated
Fitch expects Sierra’s leverage to remain high at close to 4.0x over the medium term, reflecting its reliance on borrowing to finance expansion and working-capital needs.
The company has primarily used debt to fund working capital and capital expenditure over the past 24 months. It has also raised funds through asset-backed securities to finance receivables from related parties, mainly loans to LOLC.
Its leverage more than doubled over the past two financial periods, reaching 3.9x in FY26.
Government investment provides potential support
Fitch expects government development initiatives to support growth in construction and renewable energy generation, creating additional demand for cables and improving Sierra’s operating environment.
The agency said Sri Lanka’s economic recovery remained on track, with the Government effectively absorbing the economic shocks arising from Cyclone Ditwah and the conflict in the Middle East.
Rating assessed on a standalone basis
Fitch assesses Sierra on a standalone basis, given its view that the company’s credit profile is comparable to that of its parent.
However, if LOLC’s consolidated credit profile is assessed as weaker than Sierra’s, the subsidiary’s rating is capped at one notch above that of its parent. This reflects Fitch’s assessment of ‘Open’ ring-fencing and ‘Porous’ access and control by LOLC under its Parent and Subsidiary Linkage Rating Criteria.
Fitch’s assessment of LOLC takes into account its leading position in financial services and its interests in plantations, manufacturing, trading, real estate and leisure businesses across 27 countries in Asia and Africa. The conglomerate generates most of its revenue in Sri Lanka.
The agency expects LOLC’s credit metrics to remain stable in the near to medium term. Its EBITDA net leverage was approximately 10.0x in FY26, while EBITDA interest coverage stood at 3.1x. Under its rating criteria, Fitch excludes LOLC’s finance, insurance and captive finance businesses from its consolidated assessment.
Fitch said Sierra’s standalone rating was comparable with those of Sri Lankan companies such as Singer (Sri Lanka) PLC, rated AA-(lka) with a Stable Outlook, and Vidullanka PLC, rated A+(lka) with a Stable Outlook.
Singer, one of the country’s largest consumer durable retailers, benefits from an extensive islandwide branch and dealer network. Fitch rates Sierra one notch below Singer, citing the latter’s larger operating scale and stronger liquidity, which outweigh Sierra’s lower leverage and better interest coverage ratio (ICR).
Singer’s leverage stands at 6.0x, with an ICR of 2.8x.
Vidullanka, a local renewable energy producer, carries the same rating as Sierra and has a similar operating scale, with EBITDA of approximately Rs. 2.3 billion. Its credit profile is stronger, however, with leverage of around 2.1x and an ICR above 6.0x.
Fitch said Sierra’s weaker financial profile was partly offset by lower counterparty risk, as its revenue is more evenly distributed between private and government customers and across products with varying specifications.
Fitch’s key rating assumptions
The agency’s forecasts are based on the following assumptions:
Revenue will increase to approximately Rs. 19.6 billion in FY27 from Rs. 16.0 billion in FY26, supported by improved export earnings and growth through the dealer network.
EBITDA margin will decline to 19.1% in FY27 from 20.4% in FY26 due to higher raw material prices and thinner export margins.
Expansion-related capital expenditure will amount to Rs. 500 million in FY27 for a new factory dedicated to exports, in addition to annual maintenance capital expenditure of Rs. 500 million.
Factors that could affect the rating
Fitch identified the following developments as potential triggers for a downgrade, individually or collectively:
EBITDA net leverage remaining above 4.0x for a sustained period.
EBITDA interest coverage falling below 1.5x on a sustained basis.
A deterioration in Fitch’s assessment of LOLC’s credit profile, together with a revision of its assessment of LOLC’s access and control over Sierra to ‘Open’, reflecting reduced minority shareholder influence and stronger effective control by LOLC.
The agency said it did not expect a positive rating action in the near to medium term, given Sierra’s current expansion plans are largely debt-funded.
Sierra reported cash and cash equivalents of Rs. 440.0 million at the end of FY26, against short-term debt maturities totalling Rs. 6.6 billion. Most of these short-term borrowings are used to meet working-capital requirements.
Fitch expects the company to successfully renew its short-term borrowing facilities and maintain liquidity at manageable levels.
Sierra is Sri Lanka’s third-largest cable manufacturer, supplying a broad range of products for various end-market applications.
Issuer appeal and rating committee outcome
Fitch said the issuer appealed the decision of the original rating committee and submitted additional information. Following a review, an appeal review panel determined that the new information warranted a separate appeal committee.
The appeal committee revised Fitch’s assessment of one of the key rating drivers: LOLC’s credit profile. The changes were significant enough to affect the rating outcome.
Consequently, the rating action detailed in Fitch’s latest commentary differed from the outcome reached by the original rating committee.
©2026 All rights Reserved. Asia Broadcasting Corporation Private Limited Developed by Infoxty Technologies

Loading comments…